
Overview
European real estate markets are stabilising following a sharp valuation correction, but today’s dislocation, driven by a reset in interest rates, shifts in occupier behaviour, and constrained capital availability, is creating a rare and differentiated opportunity set. For opportunistic private credit investors, real estate offers durable cash flows, inflation linkage, and meaningful diversification benefits, with historically negative correlation to public markets.
Drawing on more than €4bn invested across European real estate over 15 years, Hayfin applies a credit-oriented discipline to identify compelling opportunities across the capital structure, from acquiring quality stabilised assets at rebased entry points, to bank capital replacement, to illiquid secondary situations.
Learn how Hayfin is positioning its opportunistic credit portfolios to capitalise on this evolving market environment.
Opportunities in European Real Estate
Hayfin today announces the opening of a new office in Seoul, further expanding its presence in Asia-Pacific and reinforcing its long-term commitment to the Korean market.
Located at Three IFC in Yeouido, the heart of Seoul’s financial district, the new office will enable Hayfin to further deepen relationships with its growing base of Korean institutional investors and partners through on-the-ground coverage. The opening follows Hayfin’s management buyout, which closed in February 2025, with Samsung Life subsequently investing in the firm as a strategic minority shareholder, alongside Mubadala and AXA IM Prime. The move continues Hayfin’s broader strategic expansion across Asia-Pacific, building on the firm’s existing presence in Japan, and underscores the growing importance of South Korea and the wider Asia-Pacific region within the firm’s global investor base.
As a dedicated distribution and investor relations office, the Seoul team will focus exclusively on supporting Hayfin’s Korean investor relationships, working closely with institutional clients and partners in the market. It will be led by Sijin (Chris) Choi, who joins Hayfin with nearly two decades of experience across investments and institutional capital formation. Most recently, Chris served as Head of Private Equity APAC at UBS Asset Management, where he was responsible for regional investment and business development activities. Previously he held senior roles at Hong Kong-based Wilshire Associates and Samsung Life & Asset Management.
The new office complements Hayfin’s broader activity across the region, including South Korea’s critical importance for the Maritime investment strategy.
Carlos Pla, Head of Portfolio Management, Hayfin, commented: “The opening of our Seoul office marks an important milestone in Hayfin’s continued growth across Asia-Pacific. We have developed strong relationships with investors in the market over many years, and expanding our dedicated local presence will allow us to work even more closely with our clients and partners, providing the high level of service and engagement they expect from Hayfin.”
Chris Choi, Head of Korea, Hayfin, added: “South Korea has always been an important market within institutional capital, with a sophisticated investor base that values long-term partnerships and deep market expertise. Establishing a presence in Seoul will allow Hayfin to be closer to our clients, better understand their evolving needs, and further strengthen the relationships we have built in the market. I am excited to be joining the firm at such a pivotal point in its growth, coupled with its clear commitment to building local presence and an ambitious vision for the future.”
Hayfin has been named Private Credit Lender of the Year at the ION Analytics Mergermarket European Private Equity Awards 2026*.
The award reflects a year of significant progress across Hayfin’s private credit platform. Over the past 12 months, the firm has deployed capital across attractive opportunities in the European market on behalf of a global investor base. It continued to target middle- and upper-middle-market transactions between €100 million and €400 million, while closing DLF V, one of Europe’s largest private credit fundraises, with €15bn+.
The recognition follows Hayfin’s selection as European Large Cap Direct Lending Fund of the Year at the 2026 Debtwire Direct Lending Awards, highlighting the strength of its disciplined underwriting and its ability to execute complex transactions across markets. The annual Mergermarket Private Equity Awards, which have recognised excellence in British private equity for more than 20 years, this year expanded across Europe to celebrate the continent’s leading investors, dealmakers and advisers for their performance, innovation and impact.
“We are honoured to receive this recognition from ION Analytics, following our success at this year’s Debtwire Direct Lending Awards. This win reflects the strength of our European private credit platform, as well as the performance and commitment of our team,” said Marc Chowrimootoo, Portfolio Manager and Co-Head of Direct Lending in the Private Credit team at Hayfin. “As ever, we are grateful to our investors, partners and colleagues for their continued trust, support and partnership as the firm continues to grow.”
As of Q2 2026, Hayfin manages approximately €40 billion of assets and has invested more than €59 billion since inception.
* There is no compensation provided in connection with this award. This award should not be viewed as representative of any client’s experience and should not be taken as an indication of performance by Hayfin or any of its clients.
Three lessons from a global investor base
The €15 billion final close of the Hayfin Direct Lending Fund V was a milestone for our firm. But perhaps more interesting than the size of the fund was what we learned from the investors behind it.
Over the course of the multi-year fundraising cycle, our conversations with hundreds of institutions across Europe, North America and Asia-Pacific highlighted three key trends that we believe will shape the next phase of European private credit.
Firstly, European private credit is evolving from a predominantly regional allocation into a more strategic, global one, demanded not simply because non-European investors have discovered it or are seeking to diversify existing portfolios, but because it is a core allocation in its own right.
Secondly, how different investors access the asset class is becoming more varied and more sophisticated, driving demand for multiple tailored entry-points into one consistent underlying investment strategy.
Finally, scale is changing how institutional capital is allocated, with institutional distribution channels exerting a growing influence.
Geographic Diversification Continues to Gather Momentum
European private credit is becoming a global allocation. More than half of DLF V’s capital came from the EMEA region, including 10% from the Middle East, with the remainder broadly split between North America and Asia-Pacific. That does not reflect declining European demand – quite the opposite. European investors committed more than €6 billion to the strategy, a figure that alone would have matched Hayfin’s previous largest-ever fundraise.
What has changed is the depth of demand outside Europe. This was especially pronounced in the US, where institutions are increasingly seeking European exposure as part of broader geographic diversification within private markets portfolios. There is growing global appreciation of the characteristics of European direct lending, including diversification benefits, attractive relative value and differentiated market dynamics compared with those of more mature private credit markets. Crucially, this is not diversification for its own sake – it reflects a growing view of European direct lending as a core, strategic holding rather than a satellite one.
Recent geopolitical and trade uncertainty has added urgency to some of these conversations, but the underlying trend predates the current macro environment. Allocators have been steadily increasing their focus on European private credit in search of greater diversification over many years.
As the investor base for European private credit has become more global, so too has the need for managers to build genuinely global client coverage. Hayfin has continued to invest in its international presence, putting teams on the ground in the markets where our investors operate. That commitment is a recognition that, as European private credit becomes an increasingly important allocation within global portfolios, proximity to clients and understanding local investor needs will only become more important.
One Investment Strategy, Multiple Access Points
Different institutions have different return objectives, regulatory constraints and portfolio construction needs. As the investor base for European direct lending has become more global and diverse, the range of portfolio objectives we are asked to solve for has widened. A European pension fund, a US institution and an Asian insurer may all want exposure to the same underlying senior-secured loans, but they may not want to access that exposure in the same form.
Some investors prefer traditional unlevered commingled funds. Others seek modest leverage to target a different return profile. Still others require separately managed accounts (SMAs), evergreen structures or rated note feeders designed around regulatory or portfolio constraints.
Insurance capital is a good example of this dynamic in practice. Many insurers are drawn to the same underlying senior-secured loans as our other investors but need to hold that exposure in a form that is efficient from a regulatory perspective. DLF V’s rated note feeder, one of the first priced by a European direct lending manager, was designed with exactly that in mind: giving insurers a more capital-efficient route into the strategy without changing the underlying investment.
Similarly, while many long-standing European investors continue to favour unlevered exposure, it was important that we catered to the growing number of investors globally seeking more customised solutions. DLF V saw material growth in demand for higher risk profiles, with assets in the levered commingled fund more than doubling from DLF IV. Alongside continued use of bespoke SMAs, this helps to cater to differing risk profiles and timelines.
Crucially, the investment philosophy remains consistent. What has evolved is the architecture around it. We retain our focus on disciplined senior-secured lending and downside protection. And on a strategic level, leverage use remains conservative.
Scale Is Changing How Institutional Capital Is Allocated
The growth of private credit is also changing the diligence around the asset class. This was a defining feature of the DLF V fundraise process, with LP scrutiny of downside protection even deeper than in previous cycles, particularly around use of PIK, technology exposure and loss rates.
As allocations become larger and portfolios more complex, investors increasingly rely on investment consultants and other specialist advisers not simply for manager selection, but for portfolio construction, pacing and implementation. Investment consultant involvement in DLF V was also greater than in any prior Hayfin fundraise. This reflects the growing importance of consultants within the ecosystem, and, as a result, the value we see in continuing to cultivate key relationships within the consultant community to foster closer collaboration.
This increasing institutionalisation of private credit raises the bar for managers. Scale alone is not enough to pass muster. Institutional investors and their advisers increasingly expect repeatability, transparency, portfolio construction discipline, operational infrastructure and the ability to deliver solutions across different client types and jurisdictions.
Scale in private credit is only valuable if it improves the investor proposition. For us, that means the ability to remain selective while constructing diversified portfolios, investing consistently across market cycles and supporting increasingly sophisticated client requirements. Scale should be an outcome of repeatability, rather than an objective in itself.
Evolving Access, Enduring Discipline
The lesson from DLF V is not simply that investor appetite for European private credit is growing – it is that the market around it is becoming more global, more institutional and more sophisticated.
That evolution will require managers to do two things at once: remain disciplined in how they invest, while becoming increasingly flexible in how investors access those investments.
We believe that distinction will matter enormously in the next phase of private credit. The investment strategy can remain consistent even as the solutions around it evolve.
Taken together, our experience through DLF V points to a European private credit market entering a new phase: the investor base is more global, the ways investors access the asset class are becoming more sophisticated, and the institutional bar, sharpened by the growing role of consultants and advisers, continues to rise.
The complexity premium is the additional return available on capital solutions investments relative to traditional lending. While it can be difficult to disentangle from credit risk and other risk premia, we define it as where nuance in the asset, business, process or structure limits conventional lender participation, creating the opportunity to earn a premium return relative to a situation with similar credit risk but without the nuance.
Below we spotlight this “Complexity Premium”, which we believe is particularly apparent across Hayfin Tactical Solutions corporate primary investments.
In our view, complexity typically arises in one of three ways:
-
- Assets or companies in transition: These can include companies seeking to make strategic or transformational acquisitions, asset-backed rather than cash-flow-dependent credit profiles, and non-sponsored and management buyout transactions. Additionally, even market-leading companies operating within evolving industries struggle to borrow from the lowest cost capital providers, as the credit underwriting must be more forward-looking rather than anchored to historical trends.
- Flexible structuring requirement: Bespoke structures built around the borrower’s cash-flow profile and business plan rather than an off-the-shelf instrument. These often involve situations requiring some degree of PIK flexibility. Examples include capital that bridges to, or remains in place following an IPO or other corporate transaction, accommodates shorter or longer time horizons, or requires novel legal structuring.
- Execution complexity: This arises due to time or information sensitivity, non-traditional collateral, a requirement to reach across multiple jurisdictions, or a counterparty unable to use a traditional competitive process. These characteristics create capital scarcity and unlock the opportunity for flexible capital providers. This dynamic is further supported in the current environment by the increased demand for complex solutions due to borrowers’ need to address capital structures following a prolonged period of lower rates.
Traditional lenders can be constrained from lending into these situations due to:
- Credit metrics criteria such as the structure of the instrument, size, loan-to-value, leverage or interest coverage requirements;
- Current-cash-pay requirements and limited ability to accept structures where part of the return is delivered through PIK (even if for only a period of time), enhanced OID, contractual fees or equity participation;
- Sponsor-only mandates excluding many founder-, family- and management-owned businesses; or
- Ratings and capital treatment.
Each constraint removes competitors – resulting in either a higher return for credit risk (comparable to a traditional transaction), or disproportionate compensation for a modest increase in risk. Pricing is therefore driven by the scarcity of capable capital rather than solely by a marginal recalibration of credit risk. The comparison below shows new primary issuance in the European broadly syndicated loan and direct lending markets versus the Hayfin Tactical Solutions (“HTS”) strategy over the past two years*.
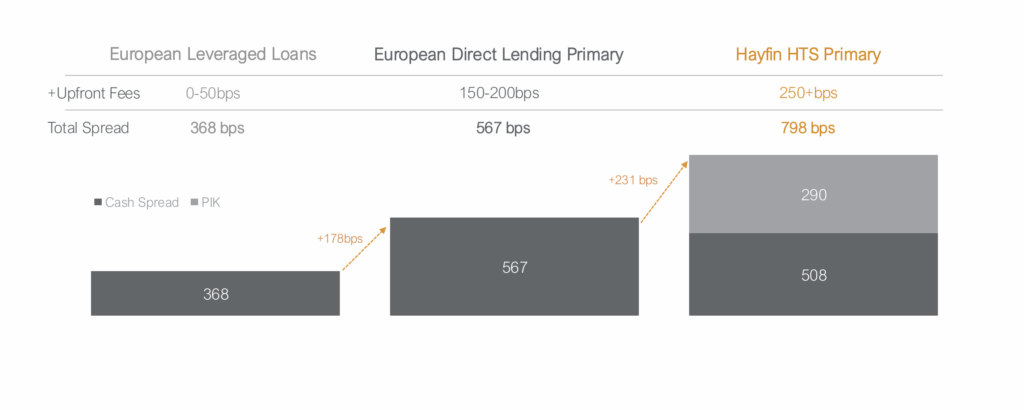
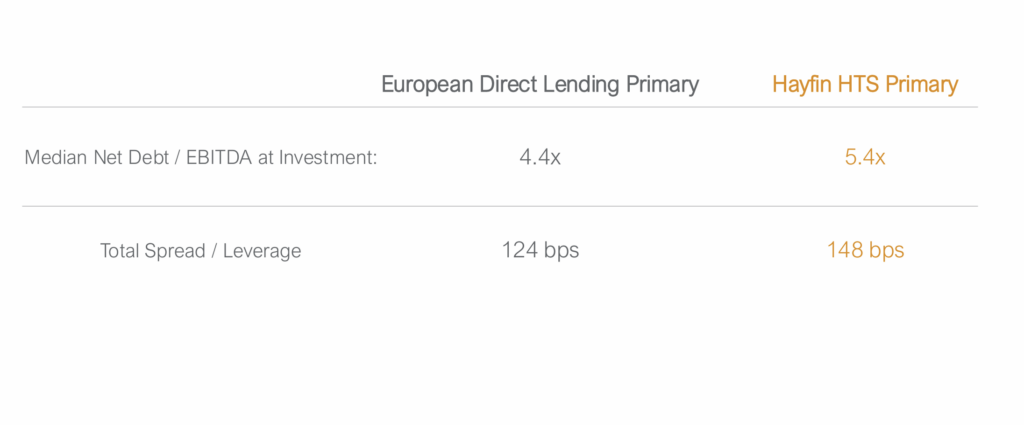
HTS investment pricing exceeds both the broadly syndicated market and direct lending, with the majority of the returns derived from cash-pay components supplemented by PIK. While leverage levels are incrementally higher on average, HTS has achieved a more attractive spread per turn of leverage, alongside higher upfront fees, supporting the view that returns are driven by complexity and capital scarcity rather than leverage alone.
Complexity must be understood to be sufficiently managed
The durability of the complexity premium depends on the ability to assess and manage risk effectively. We believe three capabilities are central to this, and are fundamental to how we evaluate, structure and execute investments in multifaceted situations:
- Sector expertise: Deep industry and asset-class knowledge, complemented where appropriate by in-house asset management capabilities, enables Hayfin to form a view where historical financial information or traditional underwriting may be incomplete or unrepresentative. Experience gained from more than 600 Private Credit investments across Hayfin’s strategies since inception provides valuable context when assessing other companies and opportunities in a particular sector.
- Bespoke structuring: Complex transactions require negotiated rather than market-standard documentation. As a result, it is possible to secure covenants, cash-flow controls, security and information rights that may be unavailable in competitive, standardised processes. For deal structuring, Hayfin relies on its dedicated in-house Legal Execution and Workouts team, who are experienced across various European creditor jurisdictions and are staffed on each deal throughout its life cycle. Most HTS primary investments have at least one covenant, at a time when covenant protection has become increasingly rare across much of the leveraged lending market.
- Prior relationships: Repeat exposure to a company, management team, borrower or sponsor reduces information gaps and is often the reason Hayfin sources the opportunity at the outset. As one of the most tenured private credit lending platforms in Europe, Hayfin frequently provides financing to the same companies over several years and at different stages of the cycle. In addition to the breadth of investments made by Hayfin in its 17-year history, the firm has developed longstanding relationships with more than 150 private equity sponsors over that period, enhancing sourcing, diligence and execution.
Case Study: Corporate Primary Lending
One of the defining characteristics of HTS is that its primary lending can earn a complexity premium without purely taking additional credit or documentation risk versus a traditional lender.
An example of this is a senior secured term loan Hayfin provided to support a take-private transaction. The public-to-private nature of the transaction meant the sponsor could engage only a limited number of financing counterparties, and whilst it had support from traditional bank lenders, there was a financing gap.
Hayfin was able to bridge this gap by providing longer-dated capital that remained structurally pari passu whilst benefiting from premium economics that included incremental loan margin and upfront fees, as well as call protection. These economics compensated Hayfin for the structuring and execution required to help facilitate the transaction for the sponsor, rather than for a weaker position in the capital structure.
This transaction highlights how HTS generates a premium by providing tailored capital solutions and executing in situations where complexity constrains traditional lenders.
Hayfin’s Tactical Solutions strategy is focused on generating a return premium in excess of traditional lending strategies by tactically allocating to investments and market segments that we believe can produce attractive returns while maintaining a conservative risk profile. The broad mandate of the strategy includes both primary and secondary lending transactions as well as asset ownership, and spans the corporate, asset-backed and securitised products markets.
For more on Hayfin’s Tactical Solutions strategy, visit hayfin.com/strategies/private-credit/tactical-solution.
* As of 31 December 2025.
Reflects new primary lending deals from 2024-2025 and excludes add on financings. Past performance is not a guarantee of future results. All investments involve risk, including possible loss of principal. See “Notes to Investment Performance” for more information on past performance, expected returns and the impact of fees on returns to investors. The investment strategy and commitments made by HTS differ from the strategy and composition of ELLI. Additionally, there are inherent limitations to the comparison of the performance of HTS and Direct Lending with the above referenced indices. ELLI represents Morningstar European Leveraged Loan Index, a market-value weighted multi-currency index designed to measure the performance of the European leveraged loan market.
Hayfin has led, as sole lender, the debt financing to support a new financing arrangement for Condis Supermercats (“Condis”), the leading proximity supermarket group in Catalonia. The funding will be provided through a €305m senior-secured unitranche facility, backed by the company’s institutional shareholder Portobello Capital (“Portobello”).
Condis is the leading proximity supermarket group in Catalonia, recognised for its convenience-led format, dense urban footprint and strong local brand. The supermarket group was founded in 1961 and is headquartered in Montcada i Reixàc, near Barcelona. Today, it operates more than 700 supermarkets, combining owned stores and franchises across Catalonia, with a main focus on the Barcelona city area, under the Condis and Condis Express brands.
The transaction was led by the Condis management team, backed by Portobello, and positions the company for its next phase of growth under continued sponsor and management ownership. The terms of the transaction have not been disclosed.
Manel Romero, CEO of Condis, said: “This transaction marks an important milestone for Condis, following our team’s work over many years to build a strong, locally-rooted business with a clear identity, convenient shopping proposition and a deep commitment to the communities we serve. With the support of Hayfin and Portobello alongside our management team, we are well positioned to accelerate our growth while preserving the values that define us. We look forward to beginning this new chapter.”
Juan Luis Ramírez, Partner at Portobello Capital, said: “We are delighted to support Condis as it continues to build on its strong track record of operational excellence. The team there have a clear strategy for long-term expansion, and this transaction highlights our continued commitment to that ambition, which has underpinned the company’s success since our entry in 2021. We look forward to continuing to work with Manel and the broader team on this exciting next phase of growth.”
Pepe Trasobares, Principal at Hayfin, said: “Condis has established a leading position in the Catalan grocery market through a strong brand, a differentiated, proximity-led model and its extensive local footprint. We’ve always been impressed by the team’s vision since our first interaction in 2019, and we’re delighted to provide this financing and support Condis as it continues to succeed.
The transaction also reflects Hayfin’s long-standing commitment to Spain, where our origination team has been on the ground for over a decade, investing more than €2.5bn of capital to date with high-quality businesses in the region.”
Hayfin is pleased to announce that it acted as sole lender in the refinancing of Norvestor-backed Serwent, a Norway-based provider of underground infrastructure maintenance (UIM) services.
Serwent provides recurring, non-discretionary traditional pipe and relining services underpinned by periodical maintenance requirements. The company serves a diverse range of customers across end-markets in the public and private sectors in Norway, Sweden and Denmark. Serwent is well-entrenched in the regional UIM market, which is poised for continued expansion with tailwinds from an ageing infrastructure stack and a tightening regulatory backdrop.
The transaction strengthens Serwent’s position on the back of its acquisition of Swoosh, and provides meaningful capacity to support its consolidation of a fragmented market.
Marco Ferrari, Managing Director, Private Credit, Hayfin Capital Management commented: “Serwent is a Nordic market leader in a resilient niche, with a competitive moat cemented in scale and regional density. We are delighted to partner with Norvestor as well as Aleksander, Fredrik and the Serwent team – supporting its expansion in Sweden with the acquisition of Swoosh and throughout the next chapter of its growth journey. The transaction reflects sustained momentum for Hayfin in the Nordics, where we continue to see a strong pipeline of opportunities for our Direct Lending strategy.”
Payment-in-kind is one of the most scrutinised features in private credit today – and one of the most misunderstood. The labels we reach for don’t always tell the full story.
The market has settled on a familiar shorthand for thinking about payment-in-kind (PIK). “Good PIK” is the PIK agreed at entry, a deliberately structured feature of the deal, priced and protected from day one. “Bad PIK” is the PIK that arrives later, typically through an amendment, when a borrower can no longer service cash interest and the lender agrees to capitalise it instead.
It is language you will hear across the industry, and as a first cut it holds up: PIK a lender chose to underwrite is generally healthier than PIK a lender was forced into. One mechanical distinction is worth drawing up front: structured PIK capitalises interest by design from day one, while a PIK toggle is an option to switch from cash to PIK on defined terms – and either form can be good or bad, so what follows applies to both.
But the shorthand misses something.
Anchoring the distinction on when the PIK was agreed assumes that origin determines outcome: that good beginnings produce good endings. They do not always, and that gap opens up a category the two-way split has no name for: PIK that was agreed at the onset, and so looks like good PIK, but was never really value-covered. Call it “Fake Good PIK”.
A PIK feature’s origin tells you how it started; it says nothing about whether the position stays covered, or whether value is slowly migrating from lender to borrower over the life of the hold. So, we are really assessing three PIKs, not two – good, bad, and fake good – and two positions can sit under the same “good” label yet end up in opposite places. Two scenarios a direct lender might face, and approach differently, show why.
Scenario one – the disciplined originator
THE SETUP
A direct lender originates a transaction with a PIK toggle built in from the outset. Crucially, the feature comes with adequate protections: the toggle can only be exercised in defined circumstances, PIK usage is capped (to a % of margin, ie there is a minimum cash pay) and time-limited in the documentation, and, importantly, any PIK is charged at a premium to the cash margin. PIK is expensive by design, which keeps the borrower honest about when they use it.
The company performs strongly throughout the hold. Some way into the investment, management identifies an attractive bolt-on acquisition and comes to us with a plan: they intend to toggle to PIK for a predefined period, at the agreed premium, to preserve cash while they integrate the target and capture synergies. Then they expect to return to cash pay.
We are comfortable with this. Our position remains well value-covered, the PIK is limited in both size, scope and duration by the documentation we negotiated, and we are being paid a premium for the flexibility we are extending. This is a healthy business using a tool we deliberately built into the structure to fund growth on sensible terms, not a borrower in distress reaching for oxygen. In due course, the company delivers on the integration, switches back to fully cash pay, and the position resolves itself cleanly.
VERDICT
Good PIK – and it earns the label. Agreed at entry, tightly protected, priced at a premium, used briefly by a performing business, and fully value-covered throughout. The structure did exactly what it was designed to do.
Scenario two – the stretch that never grew into itself
THE SETUP
A lender originates a deal that requires a PIK component from day one. The PIK is not funding a specific, time-boxed use of cash; the borrower simply wants to stretch leverage without generating the cash to service it today. The thesis rests on future growth: the company expects to grow into the capital structure, and the PIK is meant to bridge the gap until it does.
On the surface, this is “good PIK” by the standard definition – it was agreed at the onset, not bolted on later through an amendment. But the label flatters it. The growth never materialises. Rather than being a temporary feature that switches off once cash flow arrives, the PIK simply keeps running.
The balance compounds, quarter after quarter, and the PIK creeps up. And it makes little difference here whether the PIK was structured in from day one or a toggle the borrower had to trigger once the growth case slipped: the mechanism differs, but the outcome – a compounding balance that cash flow never catches up with – is the same.
The problem isn’t the mechanism itself, but what it conceals. Because cash is never generated, the lender’s return becomes increasingly back-ended: more and more of the expected value sits in a growing accrued balance that only gets realised at exit or refinancing, and only if the enterprise value is there to support it.
Every quarter of missed growth widens the gap between the notional return on paper and the cash the position has actually produced. A feature designed to bridge to growth has instead become a way of deferring the recognition that growth is not coming.
VERDICT
Bad PIK – despite ticking the “agreed at entry” box. It started clean. That didn’t save it: value has shifted into an accruing balance whose recovery depends on a growth story that never delivered.
Why the labels only get you so far
Set the two side by side.
Scenario one was agreed at entry and is genuinely positive. Scenario two was also agreed at entry, and is not.
The “good PIK / bad PIK” framing, anchored on when the PIK was agreed, misses the questions that actually matter: Is the position value-covered? Is the PIK time-limited and capped, or open-ended? Is it being paid at a premium that keeps the borrower disciplined? And is it funding a specific, self-liquidating need, or substituting for cash the business was always going to struggle to produce?
Categorising PIK is a helpful exercise, and we do it. But the labels are a starting point, not a substitute for judgement. The characteristics of each situation – coverage, protections, pricing, purpose and trajectory – are what determine whether PIK is working for the lender or against it.
At Hayfin, we address PIK usage carefully and try to get ahead of it where it matters most: at origination.
Underwriting discipline is key, we assess fundamental cashflow generation and look critically at the sustainability of capital structures taking into account potential PIK accretion. The right protections – caps, minimum cash pay, time limits, premium pricing and clearly defined toggle conditions – are far easier to secure when you are structuring a deal than to retrofit once a position is stressed. Done well, PIK is not something to be feared. It can be an effective tool to optimise performance in situations where our debt position is value-covered, allowing good businesses to fund growth without over-burdening cash flow.
So, good, bad, or fake good PIK?
As is so often the case in private credit, the honest answer is: it depends – on the structure you negotiated, the coverage you hold, and the discipline you bring to both. The label on the tin is the least interesting part.
Hayfin today announces the successful close of Hayfin Direct Lending Fund V (“DLF V”), having attracted capital in excess of €15 billion, significantly exceeding its target for the fundraise. The fundraise comprises the commingled Hayfin Direct Lending Fund V, which has reached a final close, together with related investment vehicles. At the time of the close, DLF V had already deployed more than 50% of commitments across over 35 companies.
Through its Direct Lending strategy, Hayfin sources, structures and invests in performing senior‑secured loans to primarily European middle‑market and upper‑middle‑market businesses, with an emphasis on downside protection and robust cash flow generation or asset coverage. The vast majority of these loans are originated through an extensive relationship-based primary sourcing network spanning 13 offices and dedicated sector‑specialist teams. This broad-based origination model has allowed Hayfin to build a diverse portfolio of loans to a wide range of cash‑generative businesses, with minimal exposure to software credits deemed most susceptible to AI disruption. Hayfin invested a record €7.1 billion into Direct Lending transactions in the last twelve months, bringing total strategy deployment to over €38 billion across more than 350 investments since the firm’s inception.
The fundraise attracted capital commitments exclusively from a global institutional investor base, comprising public and private pension funds, financial institutions, insurance companies, sovereign wealth funds, funds of funds, endowments, consultants and family offices. Recent strains within semi-liquid US private credit funds for retail investors have accelerated LP demand for conservative fund structures, in line with Hayfin’s approach of securing locked-up capital in closed-ended drawdown and institutional evergreen vehicles. This helped Hayfin to achieve the most significant milestone yet for its flagship private credit strategy with the successful close of Direct Lending Fund V, more than doubling the amount raised for Direct Lending Fund IV, which closed in August 2023 with over €6bn in total commitments.
The DLF V fundraise also includes the successful close of a rated note feeder which contributed approximately $600 million of total investable capital. The structure, advised on by Proskauer as Legal Counsel, provides insurers with capital-efficient access to Hayfin’s European Direct Lending strategy, reflecting the firm’s commitment to broadening access to its private credit platform across a diverse range of institutional investor types.
Mark Tognolini, Co-Chief Executive Officer and Co‑Founder of Hayfin, commented: “We are very pleased with the successful close of Direct Lending Fund V and grateful for the strong support from both new and long‑standing investors. At a time when parts of the private credit market are experiencing heightened volatility, this fundraise reflects confidence in our disciplined underwriting, our highly specialised team, our conservative approach to fund structuring and our differentiated origination model, which has been built to perform consistently across market cycles.
“In recent months, longstanding differences between the US and European private credit markets have become even more pronounced, with European lenders continuing to benefit from greater market fragmentation, continued bank retrenchment and a predominantly institutional capital base. Against this backdrop, we are well placed to take further market share and support high‑quality European businesses with flexible financing solutions – as we have consistently done in other periods of volatility – while preserving our focus on capital preservation and downside protection.”
Hayfin was advised on the fundraise by Macfarlanes.
Since it was founded in 2009, Hayfin has invested over €55bn of capital across more than 500 portfolio companies via its private credit strategies.
Hayfin has fully underwritten the debt financing to support the acquisition of Hyve Group (“Hyve”), a leading next-generation B2B events business, by Hellman & Friedman (“H&F”). H&F is acquiring Hyve from Providence Equity Partners (“Providence”) and Searchlight Capital Partners (“Searchlight”), marking the next phase of Hyve’s growth and evolution.
The senior-secured facility extends an existing lending relationship with Hyve. Hayfin first invested in the business in 2021 and then again in 2023 when supporting its take-private by Providence and Searchlight. Since then, Hyve has delivered three consecutive years of double-digit organic revenue growth, expanded EBITDA beyond $100m and built out its platform through seven strategic acquisitions and five key event launches, while investing significantly in technology and tech-enabled products and services. In partnership with H&F, Hyve will focus on accelerating international launches, expanding adjacent products and services and continuing to scale into growing end markets via its proven acquisition strategy.
Founded in 1991 and headquartered in London, Hyve operates a global portfolio of premium, must-attend B2B events connecting some of the world’s leading companies, investors, innovators and decision-makers. It operates across high growth sectors such as healthcare, ecommerce, edtech, supply chain and martech, with flagship events including HLTH, Shoptalk, Bett, Mining Indaba and Fintech Meetup. Under its current leadership team, Hyve has positioned itself as a partner platform of choice for ecosystem events in high growth markets, with a customer offering spanning content, intelligence, matchmaking and membership.
Stuart Mitchell, Director at Hayfin said: “Having first invested in Hyve in 2021, including in its most recent ownership by Providence and Searchlight, Hayfin has developed a deep understanding of the business and its exceptional growth record. During this period, Hyve has transformed into a more global, diversified and digitally sophisticated platform, with strong momentum behind it. We look forward to working with Mark and his talented team as they enter this exciting next phase of the company’s development in partnership with H&F.”
Rehan Jiwani, Managing Director at Hayfin said: “We have been lenders in the B2B events space for more than 15 years and we have on-going strong conviction in the attractiveness of the sector. Hyve is an example of an exceptionally strong platform within B2B events, and we are excited to support the company with this latest, large-scale, financing. From a Hayfin perspective, it highlights our ability to provide sizeable financing solutions that support sponsors and management teams in executing their growth ambitions.”
Completion of the transaction is expected by the end of the calendar year.